If you cannot see the graphic or access the links within this message please go to the source
|
 |
Rental housing stands out amongst fog of political uncertainty
The country’s seventh prime minister within a decade, and yet another box-fresh cabinet, are just starting to get to grips with their remits. It will be some time before we get a clear idea of what direction they will take the country in. Therefore, it’s hardly surprising that the commercial property market has been somewhat subdued of late. Add in the collapse of the ceasefire in the Middle East, and the resulting implications for inflation and interest rates, and it seems unlikely that the animal spirits of investors are going to be reawakened in the very near future. A higher trajectory for rates would be likely to have a direct impact on property yields, whilst a slowdown in the broader economy would put at risk the rental growth that has until now been the saving grace of the property market. Investors looking at offices, retail or industrial assets will be concerned about prospects for business investment, employment and consumer confidence. In relative terms however, investors in rental housing can probably look forward with a greater degree of clarity. |
Whatever the policies of the new prime minister, he is going to be battling with a problem that has challenged all six of his predecessors over the last decade. He needs to create an environment that will support the delivery of enough new homes to meet the requirements of the population. The baseline for this aspiration is not hugely promising. Housing starts and completions in the UK were both around 20% lower in 2025 than they were in 2019 (the last full-year before the pandemic). There were some signs of improvement in starts towards the end of 2025, but any hopes of a sustained recovery this year were seemingly snuffed out by the outbreak of conflict in the Middle East in February. Since then, housebuilders have responded to low sales rates and elevated build costs by slow pedaling on existing sites and cutting back hard on new ones. The net result of all this is fewer first-time-buyers and more renters, rents continuing to rise despite affordability constraints, and growing investor demand for rental housing against a backdrop of severely challenged viability. |
|
Commercial property returns
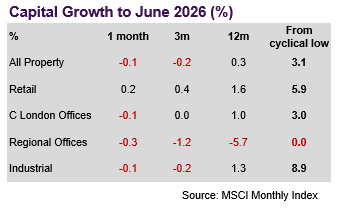
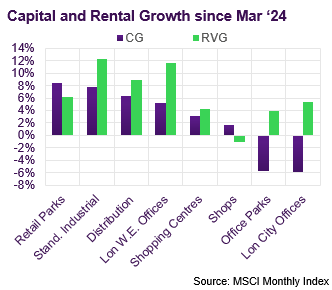
According to MSCI, average commercial property values declined by 0.1% in June and are now marginally lower than they were at the start of the year. This capital decline comes in spite of positive rental value growth, with rental values rising by 0.4% in June and by 1.4% YTD.
The Retail sector has proved to be relatively resilient; capital values edged up by 0.2% in June and by 0.7% YTD. This modest capital appreciation has been fully supported by rental value growth (+1.0% YTD). Central London Retail has delivered the strongest capital growth (4.4%) and rental growth (2.4%) so far this year. The picture for shopping centres has been more mixed, with values down by 0.5% YTD despite 2.0% rental growth.
In contrast, the Industrial sector appears to have lost momentum, with capital values edging down in June, so they are now only very marginally above where they started the year. Rental values have continued to rise (+1.9% YTD) but at a more modest pace than seen in recent years.
In the office sector, London West End continues to outperform, albeit that capital growth has slowed (+0.7% YTD). London City values are down by 1.3% YTD despite rental growth of 2.0% over the same period. The picture is weaker elsewhere, most notably in Outer London where capital values are off by 4.4% YTD and the Outer South East (-4.6% YTD). |
Investment market activity
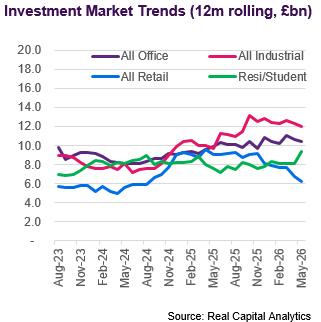
Preliminary data from Real Capital Analytics (RCA) show that £4.1 bn of transactions completed in June, marking a significant improvement from the exceptionally weak activity seen in the preceding two months. Nonetheless, Q2 was still a third lower than the same quarter last year, and the YTD total is 17% lower than the first half of 2025.
By far the largest deal to complete in June, and the largest office trade for five years, was the £750m acquisition by Barclays of their global HQ at One Churchill Place. The purchase from Canary Wharf Group demonstrates the bank’s commitment to the Docklands, and also reflects the contrast between soft valuation multiples and rapidly rising prime rents.
A number of other significant London office deals closed in June, including the £215m (5.3%) acquisition of Stirling Square in St James’ by Deka, their first London office deal for 5 years. Elsewhere, LandSec and British Land both made disposals in the City – 55 Broad Street (£63m, £640/sq ft) and 18-20 Appold Street (£25m, £622/sq ft) respectively.
EQT Exeter completed the largest logistics deal of the year so far, acquiring a portfolio of six assets from Tritax Big Box for £199m. The portfolio includes both big-box and urban logistics assets, some of which were acquired by the vendor as part of their acquisition of UKCM in 2024. Contracted income of £12m implies a yield of circa 5.7%.
Viability for new Build-to-Rent schemes may have become more challenging, but investors continue to seek exposure to the sector. Quadreal committed £120m for 241 units at London Square’s Woolwich Central development, whilst Royal London forward purchased a 225-unit scheme in Watford which is due to complete later this year. |
Market yields
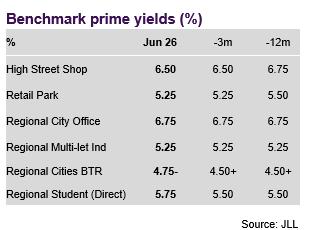
The JLL yield sheet is taking a break for the summer, providing an opportunity to compare their perception of valuation trends over the last year with their peers at Knight Frank. There are subtle differences in the sub-sector segmentation covered by each firm, and perennial debates over the definition of prime, but they nonetheless provide some interesting points of contrast.
Both firms perceive that prime high street retail yields have firmed up slightly over the last 12 months. However, whilst Knight Frank believe that prime shopping centre yields have hardened by 25-50bp, JLL judge that have remained flat throughout the last year. In contrast, whilst JLL perceive that retail warehouse yields have firmed up by 25bp since June ’25, Knight Frank have seen no reason to move their benchmarks for the sub-sector
For the Industrial sector, JLL consider that prime yields have remained stable for 12 months, whereas Knight Frank have perceived modest softening for both distribution and multi-let. For Central London offices, Knight Frank valuers have perceived some yield compression whereas JLL have seen none. For BTR and PBSA. Both firms agree that yields have softened, but Knight Frank suggest a more significant move than their peers at JLL. |
Auctions
Allsop’s commercial auction in June raised total proceeds of £33.2m, circa 20% lower than the equivalent auction last year. It was notable how many lots were sold ahead of auction, possibly reflecting the threat of a future auction as a way to incentivise buyers in the private treaty market. Almost as many lots were sold prior to auction (18) as were sold on the day (23)
This trend seemed to be particularly notable for higher value lots, with some of the highest sale prices achieved prior to auction. All 8 lots with guide prices of £1.5m+ either sold prior or didn’t sell at all. Notable pre-auction sales included a Premier Inn and attached pub, let to Whitbread until 2095 (£2.45m, 4.5%), and a convenience store leased to Asda until 2040 with CPI (£1.65m, 5.7%). |
Market forecasts
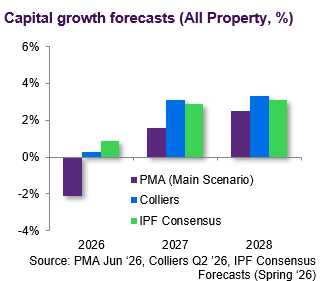
The latest forecasts from real estate adviser Colliers reflect the broad decline in sentiment for 2026 but predict that recovery will resume from next year. Colliers’ prediction of 0.3% capital growth in ’26 is a material downgrade from their previous expectation of 3.3%. However, they anticipate that this growth has merely been pushed back to 2027 (3.1%) and 2028 (3.3%).
Colliers expect Retail to prove fairly resilient despite the challenging consumer backdrop. Over 5 years, the sector is expected to be the top performer on a total return basis, at an average of 8.4% per annum. Shopping Centres, Retail Warehouses and Supermarkets are expected to outperform all other sub-sectors on a total return basis over 5 years
Colliers anticipate that office capital values will rise by an average of 2.5% p.a. over 5 years. This average masks stark differences between prime (where robust rental growth is expected to persist) and the rest. Growth expectations also vary by region, although this is reflected by yields and therefore total return forecasts are fairly consistent at around 6-6.5% per annum across regions.
Colliers are predicting the end of a long period of Industrial outperformance, with capital growth slowing to 2.0% p.a. despite solid rental growth (3.3% p.a.). On a total return basis, forecasts look unspectacular but solid at 6.7% p.a. |
Looking forward
Despite favourable demand drivers, delivering new residential rental stock to the market has become steadily more challenging. Rising build costs and higher exit yields make it hard to get the numbers stack up without heroic assumptions around rental growth. Nonetheless, within the context of a very quiet investment market there has still been a steady flow of residential focused transactions in the first half of 2026. In fact, Savills data suggest that Build-to-Rent (BTR) investment this year has been the strongest H1 total on record. However, the mix of these deals has changed materially since the early high-growth years of BTR in this country.
There have still been a smattering of forward funded or pre-purchased city centre flatted developments, but stabilised schemes and suburban houses are now attracting a far greater share of new investment. The aforementioned viability challenges have boosted demand for operational assets, reflected by the £1.5bn committed by Morgan Stanley and Greystar across two recent deals for stabilised assets in London. For new stock the pendulum has swung firmly towards Single-Family (suburban houses) in contrast to the early BTR days which were almost exclusively Multi-Family (flats). In part this latter trend has been driven by tenant demand, reflecting a longstanding shortage of high-quality family houses available to rent. However, another key factor has been the increased willingness of housebuilders to offload whole phases or even entire developments to improve cashflow predictability in an environment of muted volumes in the private sales market.
The truth is that the headwinds facing the build-to-sell market - build cost inflation, planning delays, affordability challenges and a softer employment market all point towards a supply/demand balance that favours rental housing. Hence investors will continue to deploy capital to a sector that may still be relatively immature in the UK, but that seems destined to grow many times larger over the coming decades. |
Visit us
Discover a wealth of
real estate expertise, regardless of your business level or stage.
Author
Tom Sharman
Head of Strategy
NatWest Real Estate Finance |
|
|
If you would like to opt out, please get in touch with your Relationship Manager.
The Royal Bank of Scotland International Limited trading as RBS International is registered in Jersey (no. 2304) as a private company with limited liability. Authorised and regulated by the Jersey Financial Services Commission. Registered and Head Office: Royal Bank House, 71 Bath Street, St. Helier, Jersey, JE4 8PJ. Tel. 01534 282787. Registered in the United Kingdom as an overseas company with registration number FC034191 and UK establishment number BR019279. United Kingdom business address: 250 Bishopsgate, London, EC2M 4AA. Authorised by the Prudential Regulation Authority and subject to regulation by the Financial Conduct Authority (reference number 760675) and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available on request.
Guernsey business address: Royal Bank Place, 1 Glategny Esplanade, St. Peter Port, Guernsey, GY1 4BQ.Tel. 01481 703860. Regulated by the Guernsey Financial Services Commission (reference no. 70) and licensed under the Banking Supervision (Bailiwick of Guernsey) Law, 2020, as amended, the Insurance Managers and Insurance Intermediaries (Bailiwick of Guernsey) Law, 2002, and the Protection of Investors (Bailiwick of Guernsey) Law, 2020, as amended, and The Lending, Credit and Finance (Bailiwick of Guernsey) Law, 2022.
Luxembourg business address: Espace Kirchberg, The Square, Building A-40 Avenue J.F. Kennedy, L-1855 Luxembourg. Tel. + 352 270 330 355. Authorised and supervised by the Commission de Surveillance du Secteur Financier (authorisation code: B00000399), as a branch of a credit institution originating from a non-Member State of the European Union.
This presentation is intended for information purposes only. It is not an offer or solicitation to buy or sell any products or services. The information in this document, including the opinions expressed, is indicative, constitutes our judgement as of the date indicated and is subject to change without notice. It is intended for recipient’s sole use on the basis that the recipient will make an independent evaluation of the content and seek independent financial advice. We make no representations or warranties with respect to the information and specifically disclaim all liability for any use the recipient makes of the information. |
|
|